

My phone started buzzing recently. The headlines read that Prime Minister Benjamin Netanyahu would use blockchain and crypto to evade sanctions if they were to be implemented against the State of Israel.
For people like me, who have spent years trying to get the blockchain industry to be taken seriously, this felt like an important moment. The crypto industry I work in collides with the Israeli news I read every morning, just like everyone else here.
Then reality started to sink in. In a Channel 10 interview right before Israelis took to the polling stations, Netanyahu started to fantasize about an “alternative economic system.” This might be the worst possible way for anyone to use crypto.
I’ve been following the industry closely since 2014, and today I spend most of my days working with blockchain companies worldwide. So, can a country actually use crypto to get around sanctions? Not exactly.
Magical internet money
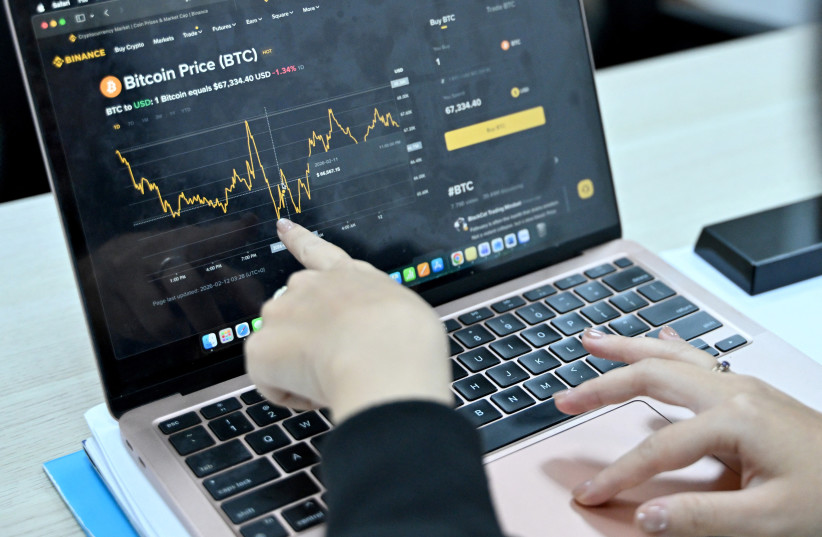
First of all, crypto is a bit of an outdated term. In the industry, we prefer blockchain or even Web3 for newer audiences. Crypto was introduced as a shared money system anyone can use, as long as they have internet access.
People in Israel don’t realize how much that actually matters because we have amazing access to banks and the global financial system. But what about the over a billion people around the world who don’t have a bank account?
Bitcoin gives people equal access to the same money (fun fact: banking the unbanked is one reason I decided to go full-time crypto).
Since Bitcoin, new developments (blockchains) like Ethereum and others have expanded what people can do with their money (like borrowing and lending). And yes, about a million tokens have been launched as “memes,” like DOGE or FARTCOIN. Most of them are useless or worse.
Finally, we have stablecoins. Tokens that are designed to equal one dollar, or whichever currency they are pegged to.
More on the digital shekel later, but basically this creates a frictionless way to send money across borders, so a designer in Brazil can get paid instantly by a small business owner in Ukraine for the new logo they commissioned.
Not so invisible
Crypto by design is transparent. A blockchain is a public ledger that’s recorded permanently. That means everyone can look up any single transaction that’s made in crypto. Starting to see why Netanyahu’s plan is flawed?
Seeing every transaction is one thing; hunting down bad actors is another, which Israel ironically (and not surprisingly) does very well.
This summer, the Defense Ministry sanctioned 37 crypto wallets allegedly belonging to the IRGC and Hezbollah – totaling over NIS 24 million.
Also, Tether, the largest issuer of US dollar stablecoins, froze $344m. in April and another $131m. in July in wallets tied to Iran’s central bank and armed forces. Sanctioned countries still need to convert their crypto to dollars, which has to go through banks.
A company called Chainalysis estimates that sanctioned entities received about $104 billion in crypto in 2025 (an 8x increase from the previous year). Russia’s ruble-backed stablecoin, A7A5, moved about $93b. in its first year.
Wallets tied to Iran’s Revolutionary Guards received more than $3b. North Korea stole more than $12b., about half of it from a single hack recently.
These numbers are a small percentage of these pariah countries’ total economies (except North Korea), which measure in the trillions for Russia, for example.
In other words, crypto works as a sanctions workaround for a small percentage of the actual economy. Most of our financial lives run through banks.
Salaries, Wolt, ATMs, mortgages – they all go through banks. Moving that entire system to crypto would take years of adoption; we can’t force it overnight because sanctions hit. And it means that the people Israel trades with would have to accept crypto even if we went full blockchain.
Could crypto one day be big enough to run a whole economy outside the banking system? Maybe. But sanctions work by cutting you off from the people you trade with, and no technology helps if no one is allowed to take your money.
Crypto can be a small, cut-off regime supplied with cash, but it can’t carry the weight of a modern open economy like Israel, which runs on foreign investment, export contracts and international venture capital.
The Bank of Israel immediately said the same just a day after the interview went live, “Cryptocurrencies cannot serve as a means of circumventing sanctions… What is right for Israel’s economy is to preserve our economic relations with our main trading partners and focus on preventing sanctions and their negative impact on the economy.” Basically, mere talk of an escape hatch is way more trouble than it’s worth.
Crypto done right
This doesn’t mean that we should avoid crypto altogether, of course; it just means it should be brought into the system, with guidelines. For example, the United States passed the GENIUS Act, the first federal stablecoin law.
The Europeans passed MiCA, which gives crypto exchanges and stablecoin companies a license to operate across Europe. Hong Kong and Singapore have built systems designed to be more friendly to the industry, rather than pushing it away. The idea is to have crypto as part of the system, not an escape hatch.
And actually, Israel is further along this path than Netanyahu’s talk suggests. In April, Israel approved the country’s first regulated shekel-pegged stablecoin. Bank Leumi is planning to let customers buy and sell Bitcoin. The Bank of Israel is deciding if it should have its own digital shekel as well.
Israel also has the people. The startup unicorns. The companies the global industry relies on that were built here.
Fireblocks, which secures digital assets for banks around the world, among other things. Bancor was one of the first DeFi (decentralized finance) protocols. Israeli analysts and builders are among the best in the world at tracking illicit crypto movements, which is exactly what makes the sanctions-bypass idea impossible.
There’s real money on the table here, too. Even when times are tough, Israeli web3 companies pulled in $405m. in 2024, according to KPMG. But the same report found the industry lost 12% of its workforce, mostly because founders and developers left for places that make it easier to operate.
So what’s taking so long? Mostly the banks.
Until now, Israeli banks simply refused to accept any money that came from the cryptocurrency industry, even from people who legally want to cash out and pay taxes. That’s finally starting to change. Just last month, the Bank of Israel told banks they can no longer turn away funds just because they came from crypto.
This is a small step, but it’s the kind of boring practical thing that threads the needle, way more than any secret plan.
Put this all together, Israel is actually a shining example of what “bringing crypto into the financial system” actually means. Shekels that can be sent and received in seconds, 24/7. Exporters get paid immediately for a fraction of the fees.
Guidelines are clear enough that companies can build here instead of going abroad to Dubai or other more crypto-friendly jurisdictions.
Governments that want to get this right don’t need a secret plan. Whoever forms the next government should finish what is already under way: one rulebook for an already flourishing industry. Crypto is a better pipe for moving money. It’s not a way around the people standing at either end of the pipe.
Netanyahu was right that Israel should be thinking seriously about crypto; he just needs to take it seriously for the right reasons.■
The writer is the chief client officer at MarketAcross, a Tel Aviv-based PR and content agency serving the blockchain industry. The views expressed are his own.